
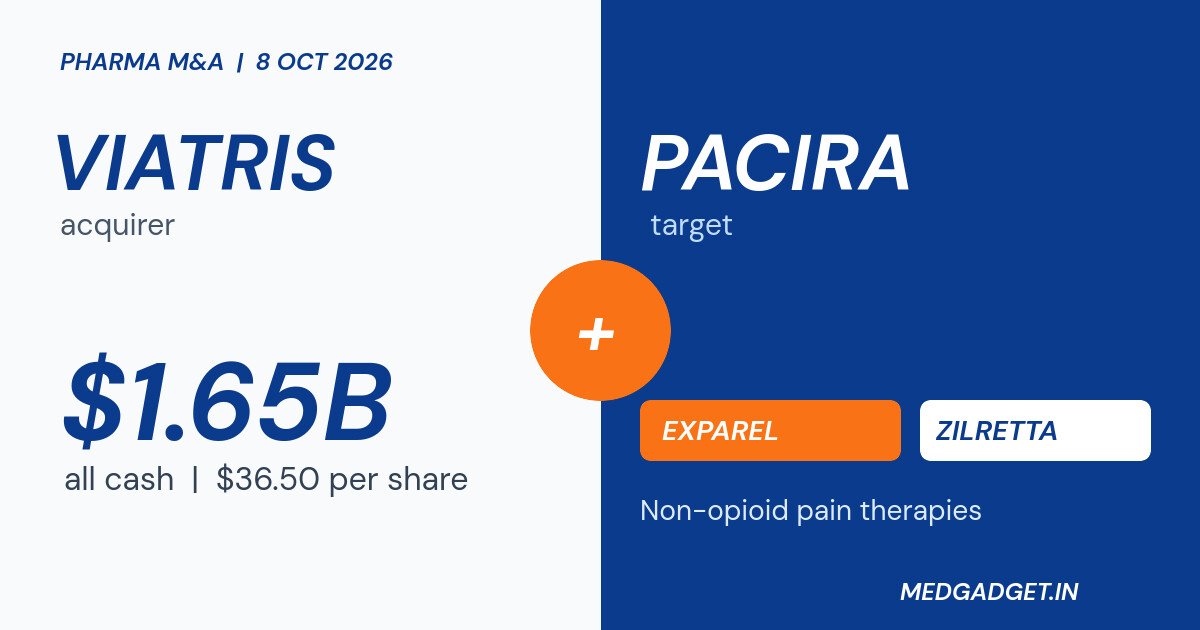
The Viatris Pacira acquisition is a $1.65 billion all-cash bet that non-opioid pain medicines will keep growing. On 8 October 2026, Viatris announced that it will buy all outstanding shares of Pacira BioSciences for $36.50 per share, giving the target an equity value of $1.65 billion. The deal adds two established products, the long-acting local anaesthetic EXPAREL and the knee osteoarthritis injection ZILRETTA, to a generics-heavy company that has been trying to build an innovative-medicines business.
Both boards have unanimously approved the transaction, and Viatris expects it to close by the end of 2026. Below we set out the deal terms, the numbers behind the price, what Viatris is getting, and the risks that the headline does not capture.
Viatris Pacira acquisition: the deal terms
- Price: $36.50 per share in cash.
- Equity value: $1.65 billion. Reports put the premium over the previous close at about 45%; the company release does not state a premium.
- Structure: a tender offer, followed by a second-step merger at the same price for any shares not tendered.
- Conditions: a majority of Pacira shares tendered and expiry of the applicable regulatory waiting period.
- Timing: expected to close by the end of 2026; the tender offer has not yet started.
- Funding: mainly Viatris’s excess cash, with the rest from short-term borrowings. Viatris expects minimal impact on its gross leverage.
- After closing: Pacira becomes a wholly owned subsidiary and is delisted from the Nasdaq.
- Advisers: Morgan Stanley, Centerview Partners and Cravath, Swaine & Moore for Viatris; Goldman Sachs and Ashurst Perkins Coie for Pacira.
What the numbers say
Pacira’s trailing twelve-month revenue to 30 June 2026 was about $746 million, with adjusted EBITDA of about $177 million and GAAP net income of just $14.6 million. The gap between those last two figures is a reminder that adjusted EBITDA is a non-GAAP measure and that reported profit is thin.
By our calculation, the $1.65 billion equity value is about 2.2 times trailing revenue and about 9.3 times adjusted EBITDA. Those ratios use equity value, not enterprise value, because the company release does not give an enterprise value, so they are rough yardsticks only. Our calculation also implies roughly 45 million shares at $36.50, and, if the reported premium of about 45% is right, a previous close near $25. Treat these as estimates rather than disclosed figures.
Separately, EXPAREL and ZILRETTA together had about $692 million in sales in 2025, around 4% growth on 2024, according to reports. That is steady rather than spectacular growth, which helps explain why Viatris is describing the deal in terms of extending product lifecycles and widening reach through its global infrastructure.
What Viatris is buying
- EXPAREL (bupivacaine liposome injectable suspension): a long-acting local analgesic used for postsurgical pain.
- ZILRETTA (triamcinolone acetonide extended-release injectable suspension): an injection into the joint for osteoarthritis knee pain.
- PCRX-201 (enekinragene inzadenovec): a locally administered gene therapy in Phase 2 for knee osteoarthritis, Pacira’s most advanced pipeline asset.
- Capabilities: US commercial, market access, medical affairs and global R&D teams.
Viatris says the products fit with its fast-acting meloxicam opportunity, a pain drug awaiting a US regulatory decision. Management also says the deal is immediately accretive to its financial guidance metrics, though it has not quantified synergies. Viatris chief executive Scott Smith called the deal an important step in building the company’s innovative medicines business, and interim chief financial officer Paul Campbell said it fits the company’s disciplined approach to capital allocation.
The patent clock: the part the headline leaves out
Reports on the deal say generic competition for EXPAREL is likely to begin in early 2030 under settlements with two generic makers, which would initially take a small share of US volume and rise to around 30% within three years. Manufacturing patents listed for EXPAREL run to 2044, but they are being challenged by two other manufacturers. ZILRETTA’s patents are reported to expire in 2031. In our assessment, this timeline is central to whether $1.65 billion proves a good price: Viatris is buying a few strong years of branded sales and will need either lifecycle management or new products to keep the value afterwards.
Why non-opioid pain matters
Long-acting local anaesthetics and joint injections are part of the effort to reduce reliance on opioids after surgery and for chronic pain. Pacira’s chief executive says the company has helped nearly 20 million patients access non-opioid pain management. Hospital formularies, however, can limit uptake of premium-priced products, a constraint that has tempered EXPAREL’s growth. The acquisition gives Viatris a recognised name in this segment rather than a new scientific platform.
For context on other deal and funding activity, see our report on the Iambic Therapeutics IPO, or browse more pharmaceutical news.
Risks and open questions
- Tender and approvals: the deal needs enough shares tendered and the regulatory waiting period to expire.
- Integration: combining a hospital-focused specialty business into a large generics company.
- Generic and patent risk: from 2030 for EXPAREL and 2031 for ZILRETTA.
- Pipeline: PCRX-201 is early, and Phase 2 gene therapy results are uncertain.
Pacira shareholders should read the tender offer documents, which will be filed with the SEC’s EDGAR database when the offer starts.
What to watch next
- Launch of the tender offer and the Schedule 14D-9 recommendation.
- Viatris’s third-quarter results and deal discussion on 5 November 2026.
- The US regulatory decision on Viatris’s fast-acting meloxicam.
- Any competing interest or challenge to the tender.
Frequently asked questions
How much is Viatris paying for Pacira?
$36.50 per share in cash, for an equity value of $1.65 billion.
When will the deal close?
Viatris expects it to close by the end of 2026, subject to a majority tender and the end of the regulatory waiting period.
What products does Pacira make?
The main ones are EXPAREL for postsurgical pain and ZILRETTA for osteoarthritis knee pain, plus a Phase 2 gene therapy, PCRX-201.
How is the deal funded?
Mainly from Viatris’s excess cash, with the rest from short-term borrowings.
When could generics hit EXPAREL?
Reports point to early 2030 under patent settlements, with manufacturing patents contested by other companies.
How we reported this: we relied on the Viatris announcement of 8 October 2026 and on reports of the deal terms. Figures labelled as ours are our own calculations. The premium and patent details come from reports, not the company release. Last updated: 9 October 2026. This article is news reporting and not investment advice.
[…] the wider Indian industry, consolidation of group entities sits alongside larger moves such as the Viatris Pacira acquisition, though the two are very different in scale. See also our report on India’s cancer drug margins, […]
[…] The release has no India-specific information. For other recent deals, see our reports on the Viatris and Pacira acquisition, Axogen’s BioCircuit purchase and BD’s $19 billion US manufacturing plan, or browse more […]
[…] and deal news in the sector, see our reports on the Stryker chief executive transition, the Viatris and Pacira acquisition, the STERIS and Xodus Medical deal and BD’s $19 billion US manufacturing plan, or browse more […]
[…] related coverage, see our reports on the margins on cancer drugs in India, the Viatris and Pacira acquisition, the STERIS and Xodus Medical deal and the Bristol Myers radiopharmaceutical trial, or browse more […]